Debt payoff
See your debt-free date, and move it closer
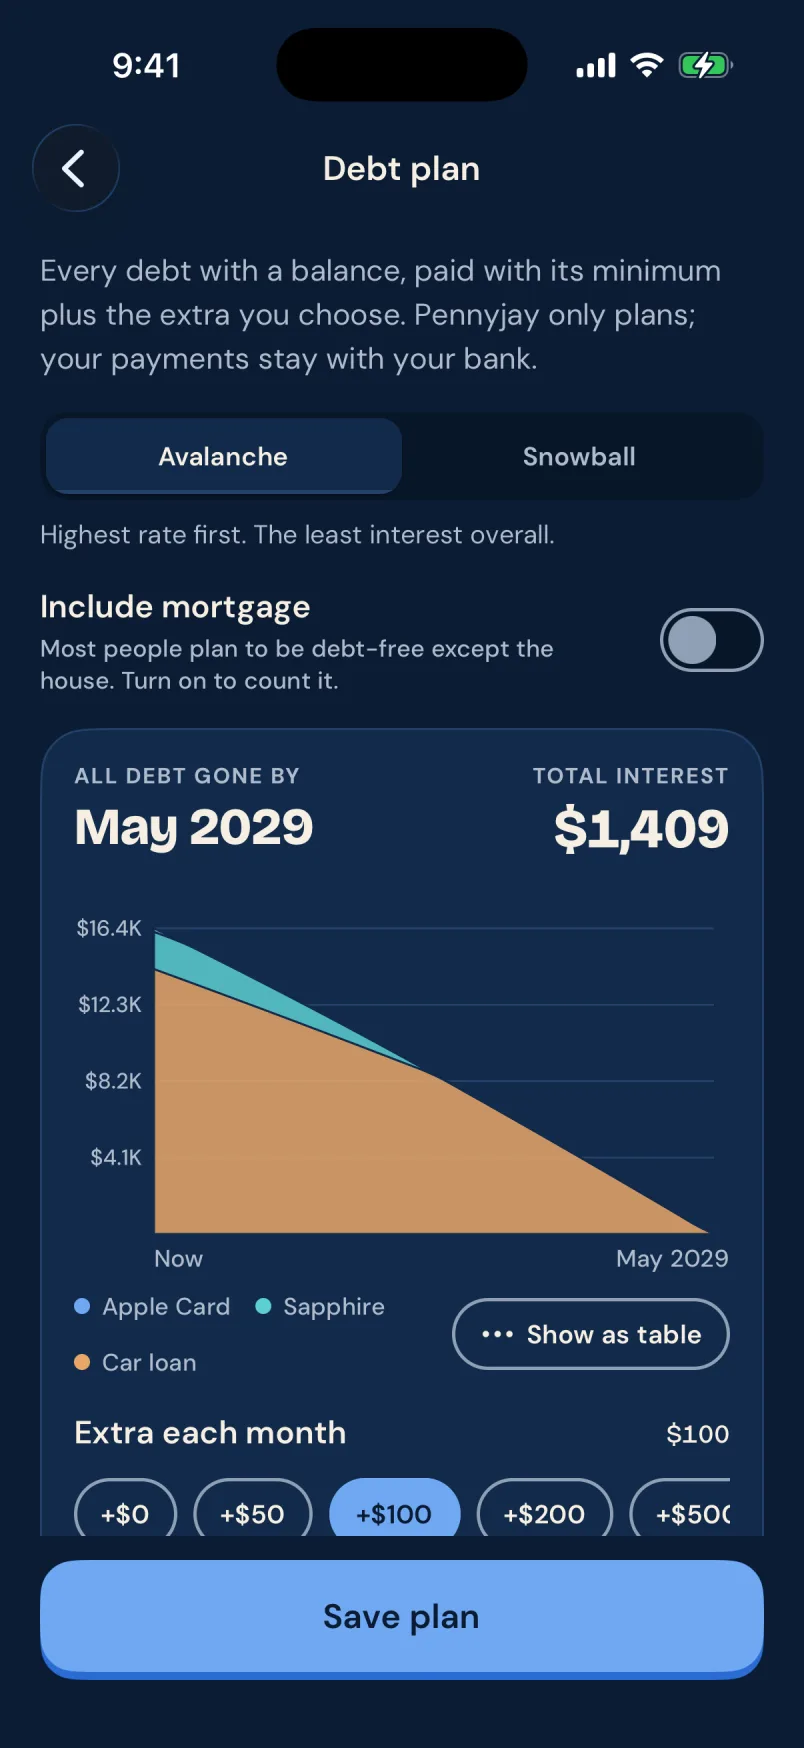
A credit card balance feels endless when all you see is the minimum. Pennyjay lays out every card and loan, picks an order to pay them off, and shows the exact month you’ll be debt-free, then how much sooner an extra $50 gets you there.
How it works
Bring in your debts
Credit cards, car loans, student loans and personal loans come in from your connected accounts. Add an APR and minimum payment where they’re missing, or add a debt by hand.
Pick a strategy
Avalanche pays the highest interest rate first and saves the most. Snowball pays the smallest balance first for quicker wins. Or focus on one account.
Slide in extra
Drag “Extra each month” or add one-time payments, like a tax refund, and watch the debt-free date, months sooner and interest saved update.
The details
A real burndown chart
Minimum payments versus your plan, month by month, so you can see the gap you’re closing.
Mortgage left out by default
Most people mean “debt-free except the house,” so the household plan leaves the mortgage out. Include it with one switch.
Extra payments get a stash
Saving a plan sets aside your extra each month in a stash, so it’s already spoken for when safe to spend is figured.
Debt-free on your home screen
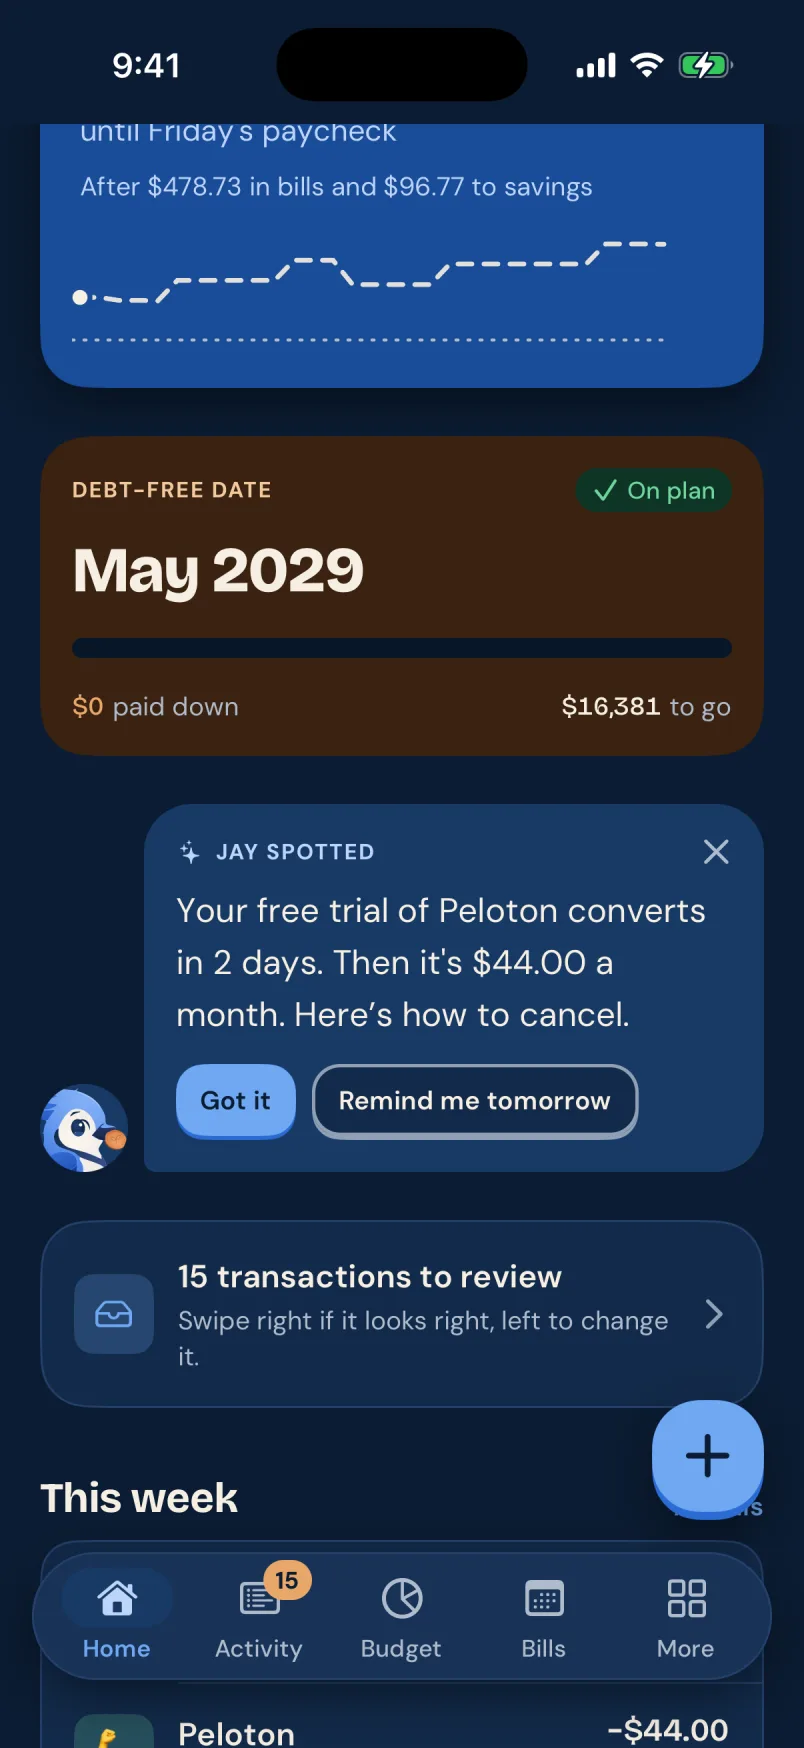
A Debt-free card on Home and a home-screen widget on iPhone and Android, with a note from Jay when a debt is paid off.
Questions
Should I use the snowball or the avalanche method?
Avalanche (highest interest rate first) costs the least in interest. Snowball (smallest balance first) pays off whole accounts sooner, which keeps many people motivated. Pennyjay shows both side by side so you can see what the difference costs.
Does Pennyjay make payments for me?
No. Pennyjay has read-only access to your accounts and never moves money. It tells you how much to pay where; you pay your lenders as usual.
What if I don’t know my APR?
Pennyjay marks estimated rates and minimums so you know which numbers to check. Look on your statement and enter the real APR to make the date exact.
Can I try the math before joining?
Yes. The free debt payoff calculator on this site uses the same snowball and avalanche approach.
More in Pennyjay
- StashesGive every dollar a job. Stash money for the car insurance due in March, a trip, or extra debt payments, right on top of your real balances. Pennyjay never moves money.Learn more
- Net worth & cash flowTrack net worth across cash, cards, investments and loans, see where every paycheck went, and follow your portfolio’s allocation and performance.Learn more
- Safe to spendSee what’s safe to spend until your next paycheck, after bills, planned savings and a buffer, with a projected balance and the math behind it.Learn more
Be first in the nest
Pennyjay is coming to iPhone and Android. Leave your email and we’ll tell you when you can download it.